The Mortgage Firm

Debt Consolidation Mortgages in London, Ontario

Credit card balances barely moving? Too many payments each month? Find out whether refinancing your mortgage could help you combine debts and make your monthly budget easier to manage.

Review My Debt Options

For homeowners in London, St. Thomas, Strathroy and nearby communities. Start with a no-obligation conversation with Marie Sanon.

Could your home equity help? See what refinancing would mean for your payments, fees and total borrowing cost before you decide.
When the bills keep coming

Making payments, but not much progress?

Between credit cards, a line of credit and loan payments, there may be little left at the end of the month. Keeping track of every balance and due date can be exhausting.

If you own your home, refinancing may let you use available equity to pay off selected debts and include that borrowing in your mortgage. Marie can help you work out whether the numbers make sense.

? Could I reduce my total monthly payments?
? Do I have enough equity in my home?
? What if my credit has taken a hit?
? Will fees or penalties outweigh the benefit?
What we will look at

A plan that fits your budget.

Combine selected debts

Bring eligible credit card, line-of-credit and loan balances into your mortgage, so there are fewer separate payments to juggle.
Check the monthly difference

Compare what you pay now with a proposed mortgage payment. A lower payment may help your budget, but a longer repayment period can cost more overall.

Work out the available equity

Your home’s current value and the borrowing already secured against it help determine what may be available. Income and credit still matter.

Compare your options

Refinancing, a second mortgage or a home equity line of credit may suit different situations. Keeping your current mortgage may make more sense.

Know the full cost

Review any mortgage penalty, legal and appraisal costs, and applicable lender or brokerage fees before deciding whether to proceed.

How it works

Start with a conversation.

You do not need to have every document ready to ask a question.

01

Tell Marie what you want to change

Share which payments are putting pressure on your budget, your approximate mortgage balance and your property location.

02

Compare the numbers

Marie reviews your equity, income, credit and mortgage terms, then explains any suitable options, payments and costs.

03

Decide with the facts

If you choose to proceed, Marie explains the documents and lender conditions. You can decide after reviewing the terms.
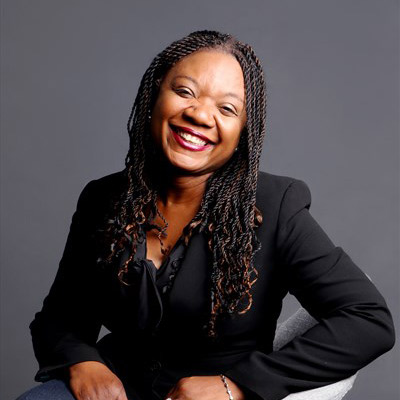
Marie Sanon, Mortgage Agent Level 2 in London, Ontario
Your London-area mortgage agent

Marie Sanon

Mortgage Agent Level 2 Licence #M19001685 The Mortgage Firm Brokerage Licence #13466

You deserve clear answers about your debt, without a sales pitch. Marie helps London-area homeowners compare mortgage options and understand what a change would mean for their budget.

The starting point is your situation: what you owe, what you can afford and whether using your home equity is a sensible next step.

Approval depends on your income, credit, property, equity and lender requirements. Consolidation does not erase debt. Moving unsecured debt into a mortgage puts your home at risk if you cannot make the payments.

Your questions, answered

Before you roll debt into your mortgage.

Straightforward answers for London and Ontario homeowners considering debt consolidation.

You replace your existing mortgage with a larger one and use the additional funds to repay selected debts. Those amounts become part of your mortgage balance. This can simplify payments, but you still owe the money and must qualify for the new mortgage.
For a typical debt consolidation refinance, lenders generally allow total borrowing up to 80% of the home’s appraised value. Existing mortgages and other secured borrowing reduce what is available, and fees can reduce the usable funds. Your income, credit and the lender’s rules also affect approval.
Possibly, but a lower monthly payment does not automatically mean lower total costs. Compare the new rate, repayment period, fees and any mortgage penalty. Spreading debt over more years can increase interest costs. A budget that avoids rebuilding the paid-off balances matters too.
You may be able to, but breaking a closed mortgage early normally triggers a prepayment penalty. Ask your lender for a payout quote. Marie can compare refinancing now with waiting until renewal or considering another suitable option. Other refinancing costs may still apply at renewal.
That does not automatically rule out every option. Lenders assess your credit history, income documents, equity and ability to repay. Some financing may cost more. Refinancing with a federally regulated bank generally requires a mortgage stress test; equity alone does not guarantee approval.
Not necessarily. A second mortgage or home equity line of credit may leave the first mortgage in place, subject to lender approval and mortgage terms. These create separate borrowing obligations. Compare the combined payments, rates and fees against refinancing the first mortgage.
Depending on the mortgage, costs may include a prepayment penalty, appraisal, legal work, discharge or registration charges, and lender or brokerage fees. Ask for a written breakdown of the costs that apply to your proposal before committing.
Marie starts by discussing your debts, property, mortgage and goals. Approximate balances are enough for an initial conversation; documents are needed for a full assessment. An enquiry is not an approval or a commitment to borrow. You can ask questions before deciding whether to apply.

Find out whether refinancing would help.

Tell Marie which payments you want to get under control. Start with a clear look at your options, the costs and what comes next.

Get Your FREE Mortgage Guides

Helpful tips, tricks and Information you need to know.

Download Now
users image

Hi, How can I help you?